Demand has changed - has Europe’s hostel market kept up?
In this blog post, we examine how demand in Europe’s hostel sector has evolved, why guest expectations are changing, and whether the market’s supply and operating models are keeping pace.
Business. Built around You.
Your expert business property advisers

Hortense Cristofari
Senior Consultant - Hotels Consultancy
European hostels are returning to focus, with owners, operators, and investors increasingly asking how the sector is evolving and where opportunities lie. Through our consultancy, valuation and transactional work, alongside regular engagement with prominent industry stakeholders through brokerage mandates, including our involvement in the refinancing of Generator Hostels’ European portfolio in 2023, and bespoke, growth-led market research, we have developed first-hand insight into the hostel sector.
This blog post is the first in a series that will draw on our experience to explore the sector today, its relationship with other accommodation segments, and the role capital could play in its future. As some operators expand while others reshape their portfolios, why does the European hostel market deserve a closer look?
Demand is expanding beyond the traditional hostel guest
The worldwide hostel market is set to rise from $8.0 billion in 2025 to $14.3 billion by 2033, as stated by Grand View Research. This represents a CAGR of 7.5%, which is more than double the projected annual growth rate of 3.6% in global Travel & Tourism GDP over the next decade, according to WTTC. Europe accounts for over a third of hostel market revenue.
Beyond the headline growth, the more significant change is the transformation of the customer base. A wider range of travellers is choosing hostels, bringing different stay patterns, room preferences and spending habits to a category once associated mainly with budget-minded backpackers. Walk into a hostel today and the crowd is likely to be more varied than a decade ago. Backpackers, educational groups and solo travellers still form the sector’s foundation, representing over half of demand in 2024, but new customer segments have developed around them. Remote and hybrid working have also brought digital nomads into the mix. Expected to reach 60 million globally by 2030, this group is drawn to affordability, activated communal spaces and opportunities to socialise, while potentially adding longer stays to a sector traditionally associated with short city breaks.
Hostels are reaching beyond their traditional demand base
New customer segments are widening hostel demand and increasing overlap with economy and midscale hotels
THE BIG PICTURE: Backpackers and solo travellers remain the foundation of demand (56% in 2024), while new segments are expanding the market and increasing overlap with economy and midscale hotels.
Demand is widening in other directions too. Families, couples, groups of friends and young professionals who might once have defaulted to an economy or midscale hotel are increasingly considering hostels, particularly where private rooms combine privacy with communal areas and social experiences. Flashpackers add another variation: independent travellers willing to trade up for design, reliable connectivity, comfort and private accommodation.
A growing overlap with economy and midscale demand
Consequently, the distinction between hostels and the economy and midscale segments is becoming increasingly blurred. Both appeal to price-conscious travellers, groups and families, but hostels can offer dormitory beds, private rooms and family rooms within one property. Choice is increasingly shaped not by a fixed customer category, but by what guests want from each trip and their preferred balance of price, privacy, flexibility and social experience. A business traveller staying in a hostel during the week may return with family at the weekend. Hostels are no longer competing to own a type of traveller, but to win a share of their trips.
A more flexible product, but no single formula
The product has adapted to this wider customer base, although not uniformly. At the design-led end, the “poshtel” model borrows elements from boutique hotels while retaining hostel affordability and social atmosphere. Reflecting interest in this format, the segment is forecast to grow at a 5.6% CAGR through 2035, according to Future Market Insights, broadly aligned with the wider sector. Yet the most consequential product decision remains the balance between dormitory beds and private rooms.
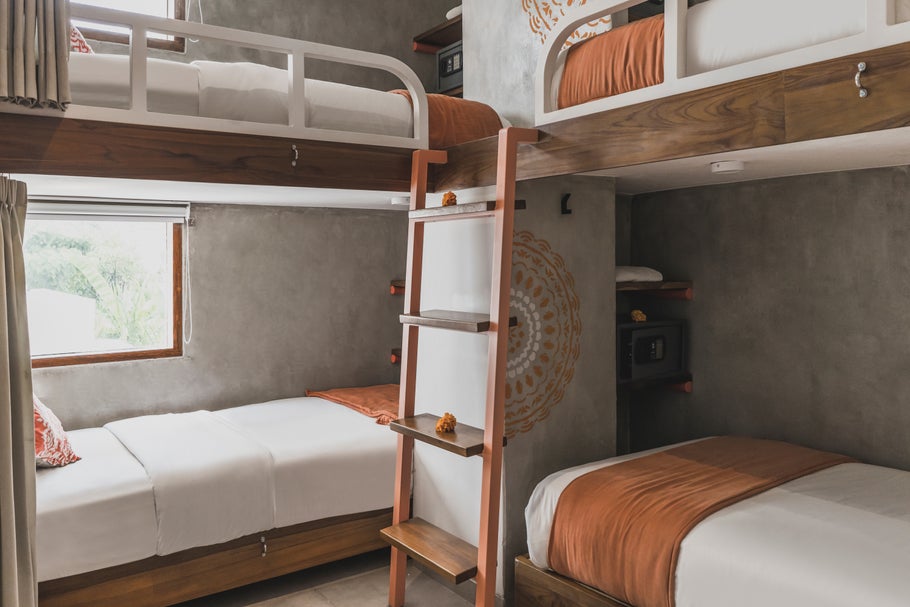
Dormitories preserve bed density and an accessible entry price, but they are evolving too. Sleep pods and enclosed beds with privacy screens, power and lighting maintain shared-room density while offering guests greater privacy. Meanwhile, private rooms allow hostels to compete for couples, families and business travellers who value the social setting without shared accommodation. No single mix works everywhere: the right balance depends on the building, location, local demand and the relative economics of a bed and a private room.
The offer has also expanded beyond accommodation. According to Hostelworld in 2024, meeting people and experiencing local culture ranked among the leading motivations for solo travellers. Communal kitchens, rooftop bars, co-working areas and organised events can make shared space central to the stay while connecting the property with its neighbourhood. By attracting local customers, these spaces can extend demand beyond overnight guests, de-risk the income mix and generate ancillary revenue.
When well calibrated, the modern hostel can therefore serve more guests across more room types and price points than the traditional model, while improving revenue productivity. What remains less common is the ability to reproduce that offer consistently across markets.
A sizeable market with limited platform scale
Europe has around 600,000 hostel beds, equivalent to approximately 170,000 hotel rooms [1], or roughly one hostel room for every 18 economy and midscale hotel rooms across continental Europe. Despite its sizeable share of the accommodation sector, concentrated predominantly in major tourist gateway cities, the hostel estate rests on a much more fragmented operator base. For every four euros generated in the European youth hostel market, around one was captured by the three largest operators, with close to three going to a myriad of much smaller operators. Bed stock shows a similar pattern, with even several of Europe’s best-known hostel groups representing only a limited share of supply.
Hostel businesses have historically kept more elements under one hat, with the same group often controlling the brand, operations and, in some cases, the real estate. This can create close alignment between concept and day-to-day delivery, but it also requires investors to assess the operating platform as an integral part of the property opportunity. By comparison, over the past 20 years the hotel sector has gradually separated ownership, operation and brand, creating a wider spectrum of opportunities and risk-and-reward combinations, and thereby attracting a greater diversity of stakeholders. Investors can choose structures involving different levels of capital, operational expertise and risk, from owning a third-party-operated branded hotel to backing the operating business itself. Hostel opportunities therefore require an understanding of both the asset and the platform behind it.
Independent hostels remain central to the sector and can succeed because they are local, distinctive and closely involved in daily operations. The investor question is not whether independents have a role, but which elements of their success can be measured, supported and replicated. In a market spread across many smaller operators, performance is more opaque and opportunities are therefore more challenging to screen at scale.
The supply question is therefore not whether Europe has enough hostel beds, but whether enough of those beds are part of products and operating models designed to serve today’s broader customer base and adapt to tomorrow’s demand. In other words, demand seems to have matured faster than the supply base and its supporting infrastructure.
Demand has matured faster than supply
This is where the story begins to move from demand to capital. A wider customer base and higher product expectations are meeting fragmented supply, while modern hostel development remains gradual and uneven across markets. The opportunity is not simply to add beds, but to support operating models combining brand, distribution, development capability and local relevance across several markets. The next article will ask whether capital, rather than demand, could reshape the European hostel sector.
The hostel market today is larger and more commercially varied than its traditional image suggests. Its core customers remain, while additional guest segments, private-room demand and more experience-led products have extended its reach. Supply has evolved less evenly, making the market, estate and operating model critical to identifying the strongest opportunities. For existing owners, growing operators and prospective entrants, the sector is increasingly relevant, but its fragmented and still opaque structure means that identifying the right opportunities requires specialist market, asset and operating expertise.
[1] Considering a ratio of 3.5 beds per room.
Sources: Hostelworld, Third Party Report, Industry Research, Grand View Research, World Travel & Tourism Council, Future Market Insights, Christie & Co Research and Analytics
To contact us for more insights and expertise on the hostel sector, please get in touch: