How snooker’s return highlights Sheffield’s untapped hotel pricing opportunity
In this blog post, Julia Huelser, Senior Consultant – Hotels, discusses how Sheffield’s strong events calendar supports demand, but highlights a persistent gap in pricing power compared to regional peers.
Business. Built around You.
Your expert business property advisers
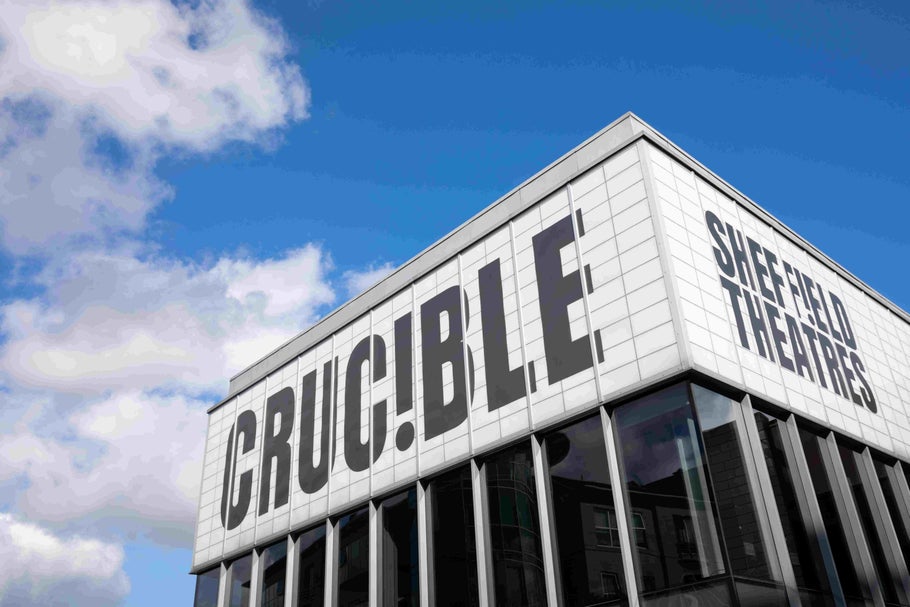
While Sheffield is unlikely to experience the global spotlight or visitor volumes associated with the FIFA World Cup, the confirmation that the World Snooker Championship will remain at the Crucible Theatre until at least 2045 reinforces the city’s status as a proven events destination. Running annually over 17 days from mid-April to May, the tournament attracts approximately 12,000 visitors to Sheffield each year, including spectators, media, officials and corporate guests, providing a consistent and reliable demand driver.
More broadly, Sheffield benefits from a wider events calendar, including the music festival Tramlines, university-related demand and conferences, which support steady levels of hotel occupancy throughout the year.
This is reflected in performance, with year-to-date May occupancy sitting in the low-to-mid 70% range, broadly in line with other comparably sized secondary UK markets, such as Bristol, Leeds, and Nottingham. However, this resilient demand base tells only part of the story. The key issue is not whether Sheffield can fill rooms, but how effectively it converts that demand into revenue.
A persistent pricing gap
While occupancy has broadly normalised, pricing remains comparatively modest. Average daily rate (ADR) sits at around £72, significantly below the regional average of approximately £95, resulting in a clear RevPAR gap versus other comparably sized regional hubs.
Figure 1: YTD May 2026 RevPAR indexed against Regional UK performance; Source: CoStar.
The city's pricing performance should also be viewed in the context of its hotel supply profile. Sheffield is heavily weighted towards the economy and upper-midscale segments, which together account for almost two-thirds of total room supply, while branded hotels represent around 86% of the market. Premier Inn, Travelodge and Mercure are the largest operators by room count, reinforcing Sheffield's position as an affordable, value-led destination dominated by recognised budget and mid-market brands. In contrast to cities such as Bristol and Leeds, where a broader mix of upscale hotels, lifestyle concepts and extended-stay accommodation creates greater pricing segmentation, Sheffield's supply remains concentrated in more value-oriented products.
As a result, rate differentiation is relatively limited, with ADRs varying by only around £13 between economy and upper-midscale hotels and a further £10 between upper midscale and upscale properties. This compressed pricing structure suggests that, despite distinct market segments, Sheffield currently has less scope to command the rate premiums typically seen in more mature regional hotel markets.
Figure 2: Share of extended stay supply, such as aparthotels and Airbnb listings, against overall hotel supply; Source: AirDNA, CoStar.
One avenue for unlocking greater pricing power may lie in further product differentiation. Compared with many regional markets, Sheffield has a relatively limited presence of extended-stay accommodation, such as serviced apartments and aparthotels, creating potential opportunities for operators to introduce concepts that better cater to longer-stay corporate travellers, project-based demand and visitors seeking more flexible accommodation options. By broadening the range of products available and creating clearer points of differentiation, operators may be better positioned to capture underserved demand segments and achieve greater rate premiums than are currently evident within the market.
That said, there are strong indications that even within the current setup more pricing yield is achievable under the right conditions. YTD May ADR increased by 2.1% year-on-year, demonstrating that demand can support rate growth when it is sufficiently concentrated. The issue is not the absence of pricing potential, but its inconsistency. Performance uplifts tend to be isolated and do not fully carry through into wider monthly or annual averages.
The real opportunity: converting demand into rate
For operators and investors, this creates a clear opportunity. Sheffield combines:
- A reliable occupancy base
- A well-established events calendar
- Limited short-term supply pressure
The next phase of performance growth therefore goes beyond generating new demand and requires extracting greater value from existing demand.
This includes:
- Refining pricing strategies around peak periods, including F&B upselling, snooker-themed activations and pop-up concepts that help capture additional spend from event-driven demand
- Improving segmentation to target higher-yield demand, with a stronger focus on premium event attendees, corporate travellers and other demand segments that demonstrate a higher willingness to pay
- Enhancing distribution and direct channel mix, while increasing visibility on channels and platforms most relevant to key segments
- Leveraging events to extend length of stay and spend, including promoting additional overnight stays to fill shoulder nights and packaging wider destination experiences to encourage guests to explore other attractions within the city
Sheffield does not have a demand problem; it has a pricing opportunity. With occupancy levels already in line with many regional markets, a strong events calendar and limited supply pressure, the key question is no longer how to attract more guests, but how to unlock greater value from those already coming. The operators that can bridge that gap stand to benefit most from the market's next stage of growth.
For more insights into regional hotel trading performance in the UK, read our UK Hotel Market Review 2026 here.
For more information about our hotel consultancy services at Christie & Co, contact: